What is house hacking?
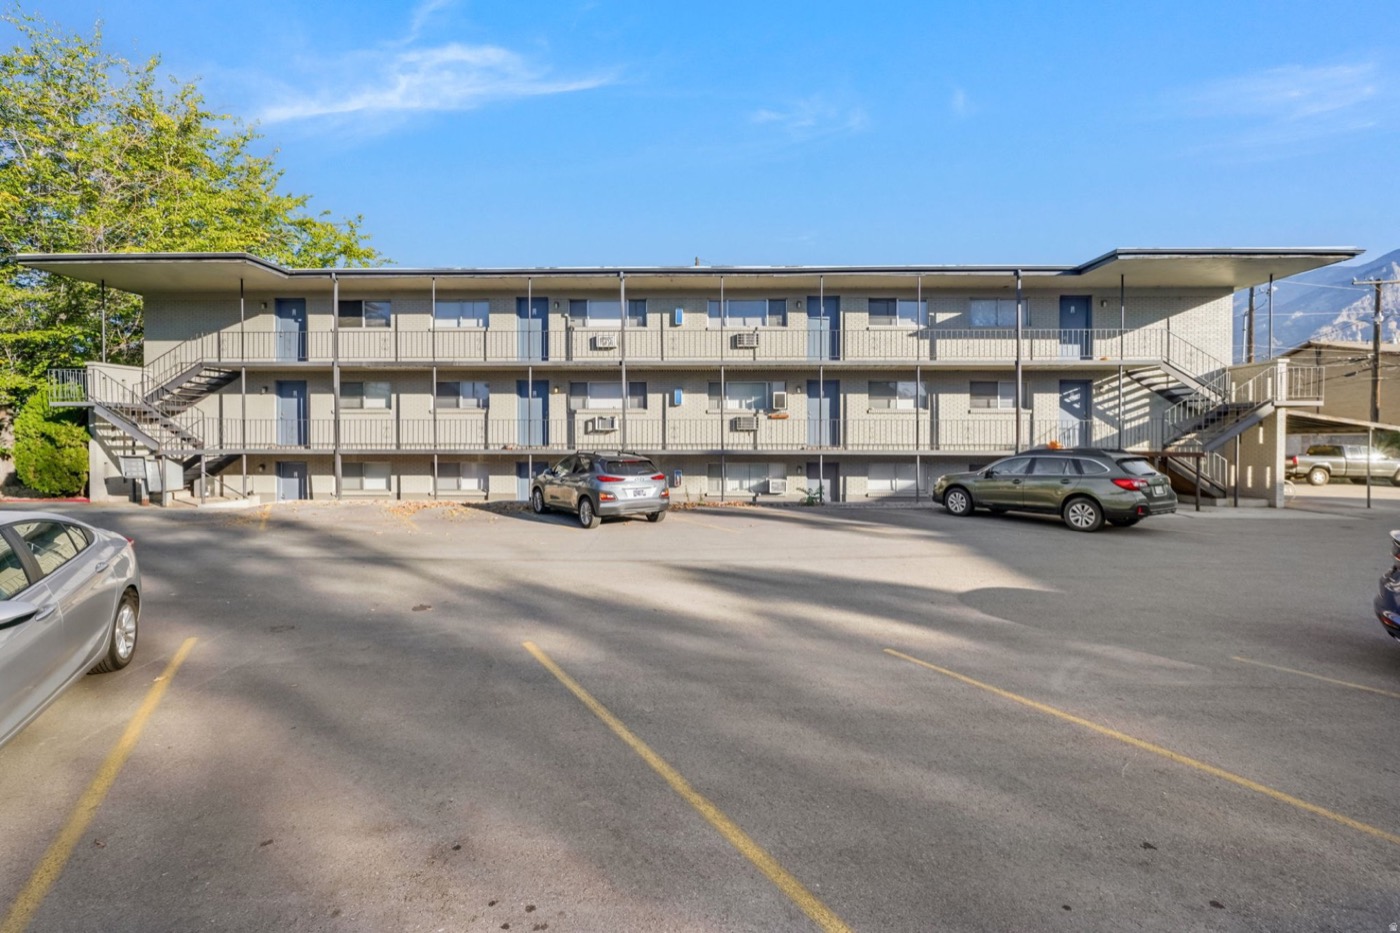
House hacking is buying a small multifamily property, living in one unit as your home, and renting the rest. Because it is your primary residence, you can use owner-occupied financing, like an FHA loan, with a much smaller down payment than an investor loan. The rent from the other units helps pay the mortgage.
When you move out later, you can usually keep the property as a rental. The FHA rule is that you must intend to live there for at least one year.
How much can I borrow with FHA in Utah County in 2026?
HUD sets FHA loan limits by county. For 2026, Utah County (the Provo-Orem-Lehi area) limits are:
| Property | 2026 FHA limit | Max price at 3.5% down* |
|---|---|---|
| Single-family | $601,450 | about $623,000 |
| Duplex | $769,950 | about $797,900 |
| Triplex | $930,700 | about $964,500 |
| Fourplex | $1,156,650 | about $1,198,600 |
*The price at which the 96.5% loan hits the limit. Above that price you can still use FHA, but you put down more than 3.5%. Limits are for the base loan, before the upfront mortgage insurance premium is added.
What are the FHA rules for buying a 2 to 4 unit property?
From HUD's Single Family Housing Policy Handbook 4000.1 (Update 18, issued August 12, 2026):
- Down payment: at least 3.5% of the value. With a credit score from 500 to 579, the loan is limited to 90% of the value.
- Move in: at least one borrower must move in within 60 days of closing and intend to live there for at least one year.
- One FHA home at a time: FHA generally insures only one principal residence per borrower, with limited exceptions.
- Counting rent: if you do not have a history of renting the property, the lender can count 75% of the lesser of the appraiser's market rent or the lease rent as income.
- Reserves: 3 and 4 unit properties need at least three months of mortgage payments in reserve after closing.
- Mortgage insurance: an upfront premium of 1.75% of the base loan, usually financed, plus an annual premium. On a 30-year loan with less than 5% down, the annual premium is 0.55% for base loans up to $726,200 and 0.75% above that, for the life of the loan.
The self-sufficiency test for triplexes and fourplexes
For 3 and 4 unit properties, the building has to support itself. The lender takes the appraiser's market rent for all units, including the one you will live in, and subtracts the greater of the appraiser's vacancy and maintenance estimate or 25%. Your monthly payment (principal, interest, taxes, and insurance) cannot be more than that number. Duplexes do not have this test.
A Utah County duplex example, with numbers
Here is a simplified illustration of a duplex in Orem:
| Purchase price | $600,000 |
| 3.5% down payment | $21,000 |
| Base loan, plus 1.75% upfront premium financed | $579,000 + $10,133 = $589,133 |
| Principal and interest at an assumed 6.25%, 30 years | $3,627 a month |
| Annual mortgage insurance (0.55%) | about $265 a month |
| Property tax (2026 Orem rate, 45% residential exemption) | about $223 a month |
| Homeowners insurance (assumed) | $150 a month |
| Total monthly payment | about $4,265 |
| Rent from the other unit (assumed) | − $1,600 |
| Your net housing cost | about $2,665 a month |
For qualifying, the lender would likely count 75% of that rent, or $1,200, as income. The tenant's unit also gets Utah's residential exemption, because it is the tenant's primary residence.
Illustration only. The price, rate, rent, and insurance are made-up round numbers, and the monthly mortgage insurance is approximate. Get real figures from your lender. Repairs, vacancy, and utilities are extra.
Why fourplexes are harder in Utah County
Take a $1,000,000 fourplex with four units at $1,500 each. The lender counts $6,000 minus 25%, or $4,500. At 3.5% down and the same assumed 6.25% rate, principal and interest alone are about $6,046 a month before taxes, insurance, and mortgage insurance. That building fails the self-sufficiency test. At prices and rates like these, a triplex or fourplex may only work for FHA with a larger down payment or higher rents. Run this test before you make an offer.
Where can you house hack in Utah County?
Duplexes, triplexes, and fourplexes are scattered across the county, and good ones do not come up often, so it helps to have a search set up before you need it. Our Provo and Orem town guides cover rental rules in two of the larger rental markets. Another option is a single-family home with a legal basement apartment, which FHA treats as a one-unit property with an ADU. Rent from an ADU can be counted, but it cannot be more than 30% of the income used to qualify. Check the city's ADU rules first. See our Utah County ADU guide.
How to buy your first house hack, step by step
- Get pre-approved for FHA and ask your lender how they will count rent and what reserves you need.
- Pick the unit count. A duplex avoids the self-sufficiency test. A 3 or 4 unit property needs the rents to carry the payment.
- Underwrite every unit: current leases, market rents, utilities, and who pays them.
- Confirm the units are legal with the city. An illegal unit can hurt the appraisal and your rental income.
- Plan the move. You need to move in within 60 days and stay at least a year.
- Plan your next step. After a year, many owners keep the property as a rental and buy again. When you are ready to trade up, a 1031 exchange can defer the tax.
New to rentals? Start with how to buy your first rental property in Utah County.
Common questions
Can I buy a duplex with an FHA loan in Utah?
Yes. FHA insures 2 to 4 unit properties if you live in one unit. For 2026, the Utah County FHA limit for a duplex is $769,950.
How much do I need down for a fourplex with FHA?
At least 3.5% of the value with a credit score of 580 or higher, plus three months of reserves. The property must also pass FHA's self-sufficiency rent test, which can be hard to pass at 3.5% down at current prices.
How long do I have to live in an FHA house hack?
At least one borrower must move in within 60 days of closing and intend to live there for at least one year.
Does the lender count rent from the other units?
Yes. Without a rental history, FHA lenders generally count 75% of the lesser of the appraiser's market rent or the lease rent.
What is the FHA self-sufficiency test?
For 3 and 4 unit properties, the appraiser's market rent for all units, minus the greater of 25% or the appraiser's vacancy and maintenance estimate, must be at least as much as the monthly principal, interest, taxes, and insurance.
Can I house hack with a basement apartment?
Yes. FHA treats a single-family home with an ADU as a one-unit property. ADU rent can be counted for qualifying, up to 30% of the income used to qualify, and the ADU must be legal under city rules.
What are the 2026 FHA loan limits in Utah County?
$601,450 for one unit, $769,950 for two, $930,700 for three, and $1,156,650 for four, according to HUD.
House hacking is how a lot of people buy their first rental without a big down payment. The hard part in Utah County is not the loan, it is finding a building where the rents make sense, especially for triplexes and fourplexes. I would rather run the self-sufficiency test and your real monthly cost before you fall in love with a property. A duplex or a legal basement apartment is often the simplest place to start.
Ready to find your first house hack?
Tell us your budget and where you want to live. Matt will send you 2 to 4 unit options and help you run the numbers. No pressure and no obligation.
Thank you.
Matt has your details and will reach out personally. If it is easier, you can text him anytime at (385) 477-8138.
Sources
- HUD, FHA mortgage limits, CY2026, Utah County
- HUD Handbook 4000.1, FHA Single Family Housing Policy Handbook, Update 18 (August 12, 2026)
- HUD, Single Family Housing Policy Handbook 4000.1 page
- Utah Code § 59-2-103, residential exemption
- Utah County Treasurer, 2026 tax rates, Orem district 90
Last updated October 2026. This guide is general education, not lending advice. Sumsion Real Estate is a real estate brokerage, not a lender. The worked examples use made-up numbers. Confirm loan terms, rates, and eligibility with an FHA-approved lender.